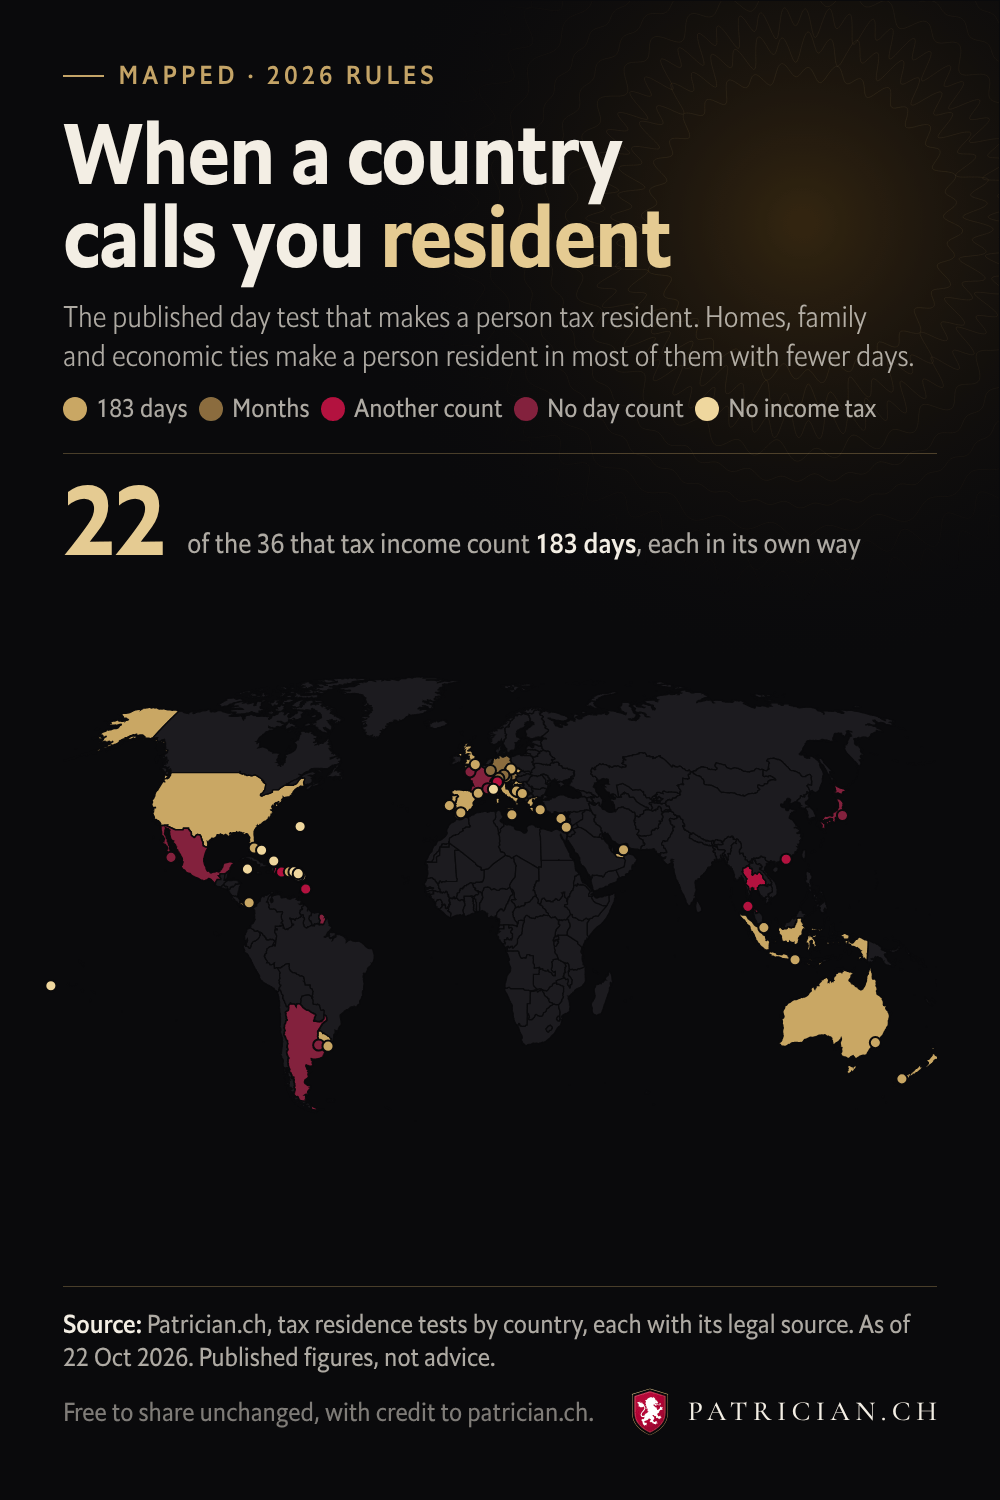
| Andorra | More than 183 days in the calendar year. Short absences count as presence unless tax residence elsewhere is shown. |
| Argentina | No day count. A foreign national becomes resident after 12 months of presence. |
| Australia | More than half the income year, the "183 day test", unless the usual place of abode is abroad and there is no intention to take up residence. |
| Austria | A stay of more than 6 months. Liability then reaches back over the first 6 months. |
| Barbados | More than 182 days in the income year. |
| Croatia | A stay of at least 183 days in 1 or 2 calendar years. |
| Cyprus | More than 183 days in the calendar year. Or 60 days, with ties to Cyprus and no more than 183 days in any other single country. |
| Czech Republic | 183 days or more in the calendar year. |
| Dominican Republic | More than 182 days in the fiscal year, in a row or not. |
| France | None in the statute. Official guidance treats a stay of more than 6 months in a year as the principal place of stay in most cases. |
| Germany | A continuous stay of more than 6 months, counted from its first day. Short breaks are ignored. A stay of up to 1 year purely for visits, recreation or a cure does not count. |
| Gibraltar | At least 183 days in a year of assessment, or more than 300 days over 3 consecutive years. |
| Greece | More than 183 days in any 12 months. Residence then starts on the first day of presence. |
| Hong Kong | More than 180 days in a year of assessment, or more than 300 days in 2 consecutive years. |
| Indonesia | More than 183 days within 12 months. |
| Israel | A presumption, not a fixed rule: 183 days or more in the tax year, or 30 days or more in the tax year and 425 days or more over that year and the 2 before it. Part of a day counts as a day. |
| Italy | Physical presence for most of the tax period: 183 days or more, 184 in a leap year. Fractions of a day count. |
| Japan | No day count. A residence held without a break for 1 year or more. |
| Jersey | No fixed day count. Visits that average more than 90 nights a year over 4 years make a person resident from year 5. |
| Liechtenstein | A stay of more than 6 months. |
| Luxembourg | A stay of more than 6 months. |
| Malta | More than 183 days in a year, by the guidance of the tax authority. |
| Mexico | None. |
| Montenegro | More than 183 days in the tax year. |
| New Zealand | More than 183 days in any 12 months. Residence ends after more than 325 days away in any 12 months with no permanent place of abode in New Zealand. |
| Panama | More than 183 days, in a row or not, in the fiscal year or the year before it. |
| Portugal | More than 183 days, in a row or not, in any 12 months that start or end in the year. |
| Puerto Rico | For the US federal test of bona fide residence: at least 183 days in Puerto Rico in the tax year, or 1 of 4 other presence tests. |
| Singapore | 183 days or more, present or employed in Singapore, in the calendar year before the year of assessment. |
| Spain | More than 183 days in the calendar year. |
| Switzerland | 30 days with gainful activity, or 90 days without. Short breaks are ignored, and the days are not tied to a calendar year. |
| Thailand | 180 days or more in the tax year, over 1 stay or several. |
| United Arab Emirates | 183 days or more within 12 consecutive months. Or 90 days or more for a UAE or GCC national or a residence permit holder with a permanent home, a job or a business in the UAE. |
| United Kingdom | 183 or more days in the tax year. |
| United States | The substantial presence test: 31 days in the year and 183 days over 3 years, counting 1/3 of the days in the year before and 1/6 of the days in the year before that. |
| Uruguay | More than 183 days in the calendar year. |
| Antigua and Barbuda | Employment income has not been subject to income tax since 1 July 2016. The Income Tax Act still defines a resident: a permanent home in Antigua and Barbuda with some presence in the year, 183 days or more of presence, a shorter stay that runs on from or into a year of 183 days or more, or 30 days or more for the holder of a permanent resident certificate. |
| Bahamas | No direct taxation laws, and so no domestic provision that defines tax residence or sets criteria for it. |
| St Kitts and Nevis | Income tax on individuals was abolished in 1980. The tax residence guidance of the Inland Revenue Department covers companies. |
| Anguilla | A tax residence certificate under the Economic Residence Act: at least 45 days in Anguilla each calendar year, fewer than 183 days in any other country, an annual lump sum tax of US$75,000 and approved property of US$400,000 or more. |
| Bermuda | No income tax on individuals. The note Bermuda gave the OECD sets out no tax residence test for a person. |
| British Virgin Islands | No income tax is levied. The territory levies payroll tax, property taxes and stamp duty. |
| Cayman Islands | No direct taxes, and no provision of Cayman law that defines tax residence. |
| French Polynesia | No general income tax on individuals. The tax office issues no tax residence certificate, only an attestation that a person is registered for the taxes it manages. |
| Monaco | No income tax on residents, except French nationals under the 1963 convention with France. A residence certificate for tax purposes goes to a permit holder who meets 1 or more of 3 conditions: more than 183 days in Monaco, a principal place of business in Monaco, or the majority of the year spent in Monaco. |
| St Barths | Tax domicile in St Barths starts only after 5 years of residence. For the first 5 years a new resident is taxed as a French resident. |
| Turks and Caicos | No direct taxation laws, and no provision of local law that defines tax residence. |